The State of Growth Equity, measured the same way every year.
Our read on the passage between venture capital and private equity: who funds it, what it asks of a company, and where the companies that stall in it actually stall.
A LeverVenture research series on growth equity.
The State of Growth Equity is a research series from LeverVenture, and this is its first edition. It covers growth equity across the United States, Europe and Israel, read from a life sciences and healthcare mandate, with artificial intelligence as the accelerant inside it.
What it measures
The middle seat itself. How companies arrive in it, what the passage costs them in time and attention, and which capability gap most often decides whether they cross it.
How it is built
Primary industry data from market data providers, regulatory filings, and company and fund disclosures, cited inline and consolidated in the references. The method sits in the appendix, and where a figure is estimated or triangulated the basis is disclosed on the page it appears on.
Who it is for
Family offices, high-net-worth individuals and strategic allocators, and the operators running the companies the study is about. It is written to be useful to both, which is why the method sits in the body rather than an appendix nobody opens.
The findings, free and complete.
The summary is not a teaser. It is the same text that opens the report, with the charts that carry a finding, published without a form in front of it.
actually breaks
Illustrative
| Gate | Share of cohort | Scale |
|---|---|---|
| Commercial proof | 34% | |
| Manufacturing and supply scale | 22% | |
| Market access and reimbursement | 19% | |
| Leadership depth | 15% | |
| Capital sequencing | 10% |
Figure 1 is illustrative. It is drawn to show the shape of the finding and the way the report reports it, not to publish this edition’s data set. The observed figures, the cohort definition and the method that produced them are in the report itself, each on the page where the number appears.
Every finding the summary carries, in the order the report makes them. Nothing here is held back for the full report; the evidence behind each one is.
The gap is a capability gap before it is a capital gap
Companies that stall in the passage are rarely short of conviction and rarely short of a market. They are short of one function — a commercial motion, a quality system, a market-access argument — at the moment that function becomes the whole company.
The operating wrap is the variable most often left unpriced
Operating help is described qualitatively almost everywhere and specified almost nowhere. The edition argues that a wrap nobody named is a wrap nobody can hold anybody to.
The capital continuum is broken at Series A-plus
Seed is oversupplied and mature earnings are well served by private equity. The money in between has thinned: graduation from seed to Series A within twenty-four months has halved to 15.4 percent, and the crossover funds withdrew. The break sits exactly where durable companies are built, which makes it an entry window rather than a warning.
Smaller funds are out-earning the megafunds
Pooled net internal rate of return runs roughly 770 basis points ahead for smaller growth-equity funds against the megafunds across 2018 and later vintages. The spread is structural rather than a vintage accident, and it is the reverse of the prior decade.
Convergence is the dominant exit pattern of the decade
About 46 percent of billion-dollar exits between 2023 and 2025 span two or more sectors. A single-mandate fund cannot diligence the half of a convergence company that sits outside its mandate, so it either misses the round at entry or pays the premium at exit.
The capital gravity of artificial intelligence has starved everything else
Artificial intelligence took 63.3 percent of United States venture dollars on 38 percent of the deals, while health-focused artificial intelligence still clears about 56 percent below general artificial intelligence at Series A. That discount is the cheapest frontier entry of the cycle for an investor who can add clinical, regulatory and commercial weight.
Returns are made by operators, not by multiple expansion
More than half of the value created in top-quartile deals now comes from operating improvement, against roughly a third between 2014 and 2019. At the best funds one operator carries two or three companies; at megafund scale the ratio is one to four or worse.
Liquidity is a design choice
Roughly 1,200 venture-backed companies now sit with no clear exit path, and the listing window is effectively closed to most of them. Acquisition cadence and secondaries optionality, designed in from the start, beat waiting for an offering that may never come.
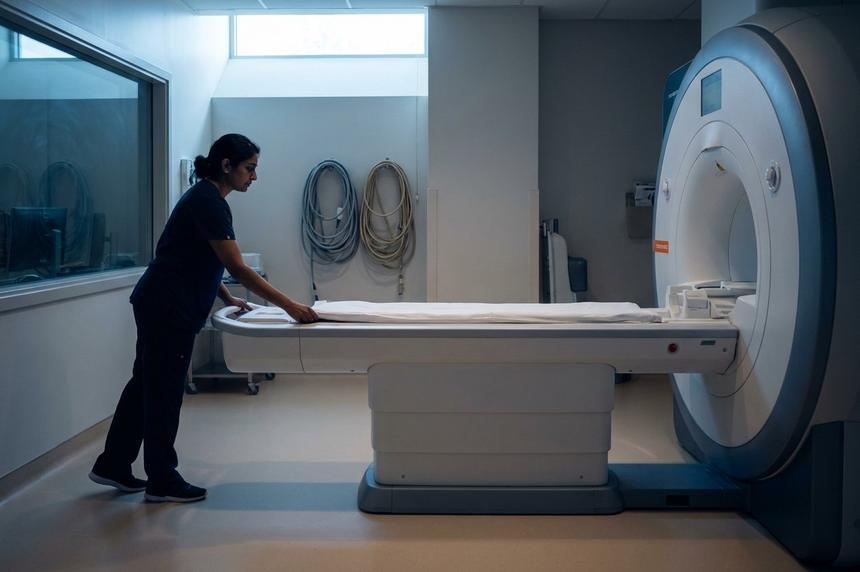
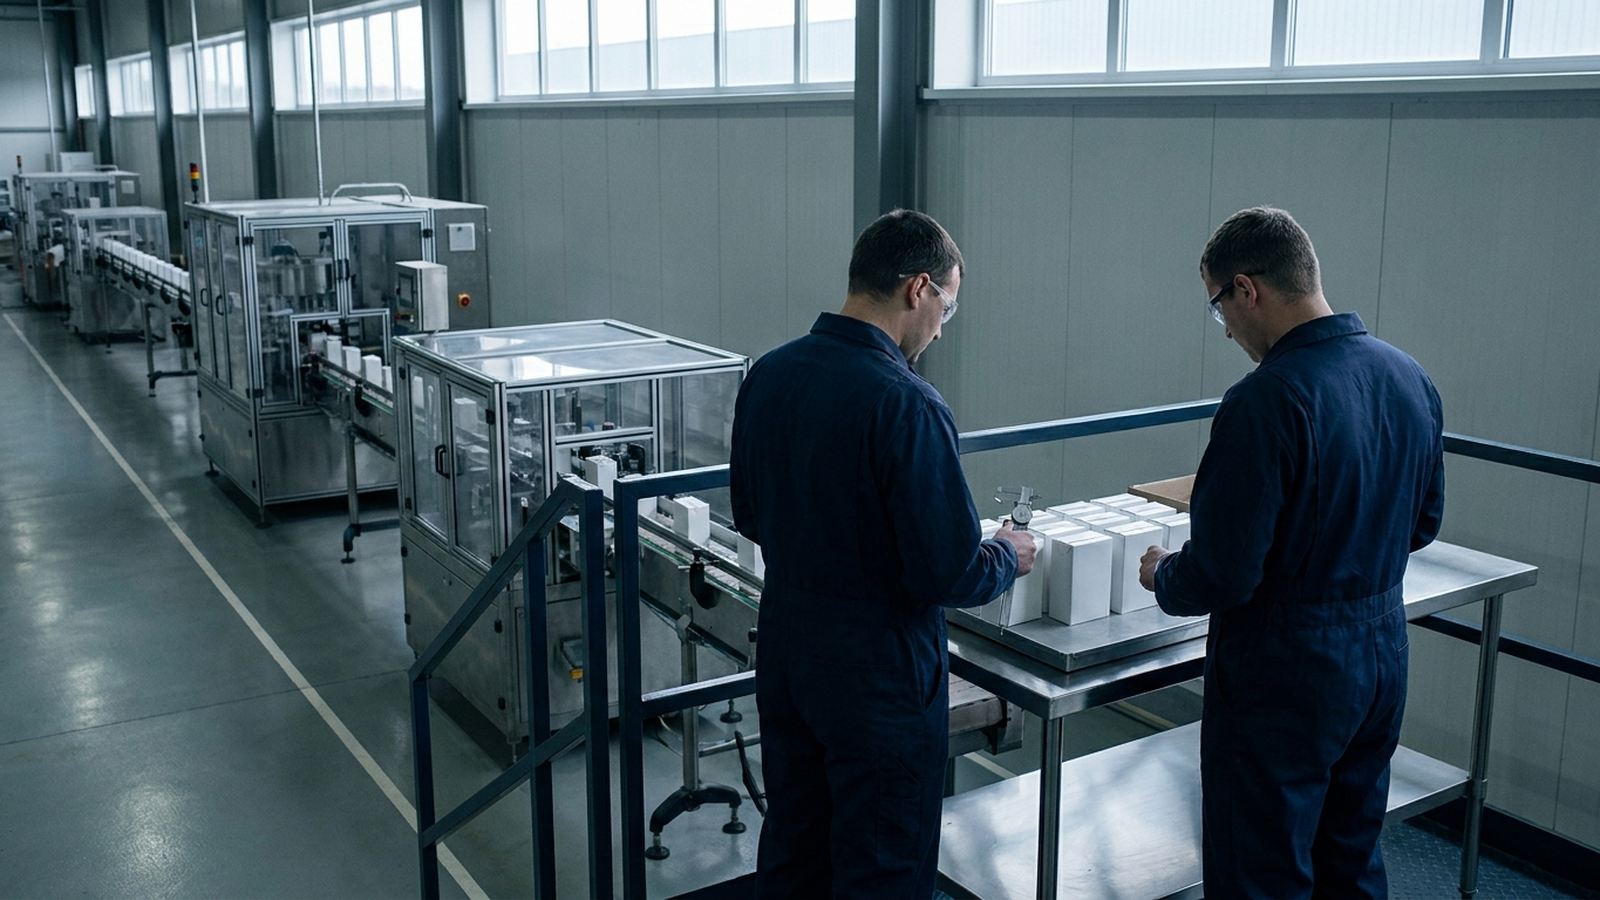
Two of the gates in Figure 1 are physical, and are shown here in the places they occur. The other three — market access and reimbursement, leadership depth, and capital sequencing — are commercial and organizational, and the report argues them in text rather than pictures.
The full report, sent by a person.
The complete data set, the underlying method, the company-level tables and the appendix. Requested here and sent from a named address, usually within one business day.
The State of Growth Equity
Full report · 192 pages
Published annually from 2026
The findings, the method and every chart that carries one. Complete, not a teaser, and the same text that opens the full report.
The complete data set, the underlying method, the company-level tables and the appendix. Sent by a person, not by an autoresponder.
A partner will send the report from a named address. This board is a design prototype, so nothing was transmitted.
The first edition, 2026.
This is the first edition of the series. Each edition after it covers the same ground, so readers can compare one year with the next.
The current edition is sent on request, from a named address. You are welcome to cite the study; the opening pages of the report show how.
Ask for the report, the executive summary, or the method behind a particular figure.